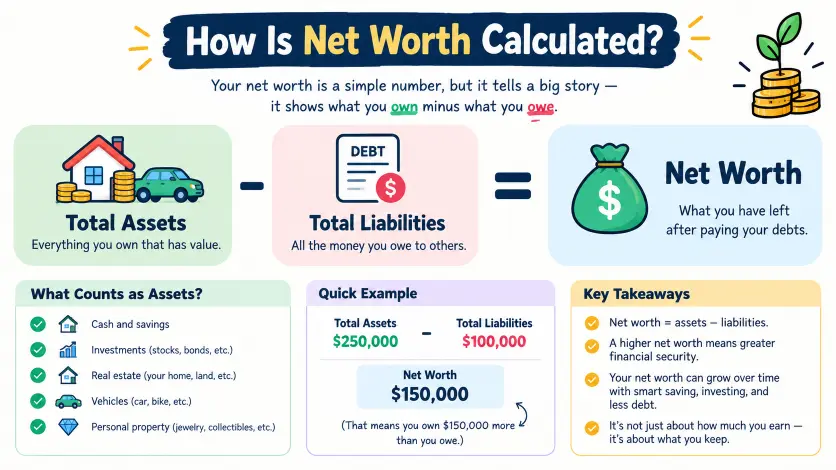
Ever wondered how websites and financial publications arrive at a person’s net worth? The number is not simply the amount of money someone earns or has in a bank account. Net worth is generally calculated by adding the value of a person’s assetssuch as cash, investments, real estate, businesses, vehicles, and other valuable propertyand then subtracting their debts and other liabilities.
For public figures, however, the calculation can be more complicated because many assets and financial obligations are not publicly disclosed. As a result, celebrity and entrepreneur net worth figures are often estimates rather than audited financial statements.
Understanding how net worth is calculated helps readers distinguish between documented financial information and online estimates. A reliable calculation starts with identifiable assets and liabilities and uses reasonable, current valuations where possible.
Public records, company filings, property information, reported earnings, and credible financial sources may help researchers build an estimate, but they cannot always reveal private debts, taxes, ownership percentages, or expenses. That is why responsible net worth reporting should clearly distinguish verified figures from estimates and explain the evidence behind the calculation. In this guide, we break down the net worth formula, major asset categories, liabilities, valuation methods, and the factors that can make a reported net worth change over time.
The Basic Net Worth Formula
The simplest way to understand net worth is:
Assets − Liabilities = Net Worth
For example, imagine someone has:
| Financial Item | Value |
| Savings | $50,000 |
| Investments | $100,000 |
| Home value | $300,000 |
| Car value | $30,000 |
| Total Assets | $480,000 |
| Mortgage | $220,000 |
| Car loan | $10,000 |
| Credit-card debt | $5,000 |
| Total Liabilities | $235,000 |
| Net Worth | $245,000 |
The calculation is:
$480,000 − $235,000 = $245,000
Therefore, the person’s estimated net worth in this example is $245,000.
What Counts as an Asset?
An asset is something a person owns that has financial value.
Common assets include:
1. Cash and Bank Accounts
Money held in checking and savings accounts is generally straightforward to include because its value is directly observable.
2. Investments
Stocks, bonds, mutual funds, exchange-traded funds, and other investments can contribute to net worth.
Because market prices change, the value of these assets can rise or fall from one day to another.
3. Retirement Accounts
Retirement accounts can also form part of a person’s overall assets. The exact treatment can depend on the purpose of the calculation and whether taxes or penalties would apply if the funds were withdrawn.
4. Real Estate
A home, rental property, vacation property, or other real estate can be counted using an appropriate current value.
If a person owns a $700,000 house but has a $500,000 mortgage outstanding, the property contributes approximately $200,000 of equity before considering other factors.
5. Vehicles and Personal Property
Cars, boats, jewelry, collectibles, artwork, and other valuable possessions may be included when they have meaningful resale value. Fidelity lists vehicles and valuable personal property among potential assets in a personal net-worth calculation.
6. Business Interests
A person who owns part or all of a private company may have a business interest that contributes to net worth.
This is one area where calculations can become difficult because privately held businesses generally do not have a continuously quoted public-market price.
What Counts as a Liability?
A liability is money or another financial obligation that a person owes.
Common liabilities include:
- Mortgage balances
- Credit-card debt
- Student loans
- Auto loans
- Personal loans
- Home-equity loans
- Business-related debt
- Other outstanding obligations
For example, a $400,000 house can be an asset while its $300,000 mortgage is a liability. The two figures should not be confused.
The Consumer Financial Protection Bureau similarly explains personal balance sheets as a comparison between assets and liabilities, with the difference representing net worth.
How to Calculate Your Net Worth Step by Step
Step 1: List Your Assets
Write down everything you own that has measurable financial value.
For example:
- Bank accounts
- Investments
- Retirement accounts
- Real estate
- Vehicles
- Business interests
- Valuable personal property
Step 2: Determine Current Values
Use current or reasonably supportable values rather than what you originally paid.
For publicly traded investments, market prices can provide an observable value. For a home or private business, valuation may require an estimate.
Step 3: Add Your Assets
Calculate the total value of all assets.
Total Assets = Asset 1 + Asset 2 + Asset 3 + …
Step 4: List Your Liabilities
Add all debts and financial obligations that should be included.
Step 5: Add Your Liabilities
Calculate the total amount owed.
Step 6: Subtract Liabilities From Assets
Use the main formula:
Total Assets − Total Liabilities = Net Worth
Charles Schwab’s personal net-worth worksheet uses the same basic structure, separating assets and liabilities before calculating net worth.
How Is Celebrity Net Worth Calculated?
This is where the question becomes more complicated.
When people search for the net worth of a celebrity, athlete, musician, actor, influencer, or entrepreneur, they may find different estimates from different websites.
A celebrity’s exact financial position is usually not publicly available in full. Therefore, an online net-worth figure can represent an estimate rather than an audited personal balance sheet.
A researcher may examine publicly available information such as:
- Reported salaries or fees
- Publicly reported business ownership
- Investment information
- Real-estate records
- Company ownership
- Endorsement deals
- Public filings
- Reported contracts
- Known assets
- Reported debts, when available
The researcher then attempts to estimate the person’s assets and liabilities.
Example
Suppose publicly available information suggests that a celebrity owns:
- Real estate worth approximately $8 million
- Investments worth approximately $12 million
- Business interests estimated at $15 million
- Other assets estimated at $2 million
That produces approximately:
$8M + $12M + $15M + $2M = $37M in assets
If estimated liabilities were $7 million:
$37M − $7M = $30M estimated net worth
But this does not necessarily mean the celebrity’s verified net worth is exactly $30 million.
The valuation of private businesses, property, investments, taxes, debts, ownership percentages, and undisclosed assets can all affect the result.
Why Do Net Worth Estimates Differ?
Different websites can publish substantially different numbers for the same person.
This does not necessarily mean that one calculation is deliberately wrong. Several factors can explain the difference.
Private Financial Information
Most individuals do not publicly disclose every bank account, investment, debt, or property.
Changing Asset Values
Stocks, cryptocurrencies, businesses, and real estate can change in value.
Private Company Valuations
A private business does not always have an easily observable market value.
Ownership Percentages
A celebrity might be associated with a company without personally owning 100% of it.
Debt
A published estimate may identify assets but have little reliable information about outstanding liabilities.
Different Valuation Dates
A $20 million estimate from one year may not be comparable with a $20 million estimate from another date.
Gross Earnings vs. Net Worth
This distinction is especially important.
Earnings are not the same thing as net worth.
Someone might earn $10 million over several years, but taxes, expenses, investments, spending, and debt determine how much of that income ultimately contributes to wealth.
Is Income the Same as Net Worth?
No.
Income measures money received during a period, while net worth represents the difference between assets and liabilities at a particular point in time.
For example:
- Person A earns $500,000 per year but has $400,000 of debt.
- Person B earns $150,000 per year but has $2 million in assets and little debt.
Person A has the higher annual income, but Person B could have the higher net worth.
Fidelity notes that income alone does not determine net worth; savings, assets, and debt also matter.
What Is a Positive or Negative Net Worth?
A person has a positive net worth when their assets are worth more than their liabilities.
Positive Net Worth
$600,000 assets − $250,000 liabilities = $350,000 net worth
A person has a negative net worth when liabilities exceed assets.
Negative Net Worth
$100,000 assets − $180,000 liabilities = −$80,000 net worth
A net worth of zero means assets and liabilities are equal.
These outcomes are normal financial measurements rather than judgments about a person’s income or lifestyle. Fidelity specifically notes that net worth can be positive, negative, or zero depending on the relationship between assets and liabilities.
Net Worth vs. Cash: What’s the Difference?
Net worth is not the same as the amount of cash someone has available.
A person could have a $2 million net worth but only $100,000 in cash.
The remaining wealth could be tied up in:
- A house
- Retirement accounts
- Stocks
- A private company
- Vehicles
- Other assets
Likewise, someone can have substantial cash but significant debt.
This is why net worth provides a broader picture than looking at a bank-account balance alone.
How Often Should Net Worth Be Calculated?
There is no universal requirement for how frequently an individual should calculate net worth.
Someone tracking personal finances might calculate it:
- Monthly
- Quarterly
- Every six months
- Annually
The important factor is consistency.
Charles Schwab recommends calculating personal net worth annually as part of financial planning, while also emphasizing the value of tracking changes over time.
For investments that fluctuate significantly, more frequent tracking may produce large short-term changes that do not necessarily represent a long-term trend.
Does a House Increase Net Worth?
Potentially, yes.
A house is generally an asset, while the mortgage attached to it is a liability.
For example:
Home value: $500,000
Mortgage balance: $350,000
Approximate home equity:
$500,000 − $350,000 = $150,000
That $150,000 contributes to net worth, subject to the assumptions and valuation method being used.
This illustrates why simply looking at the purchase price of a property can give an incomplete picture.
Does a Car Count Toward Net Worth?
Yes, a vehicle can be included as an asset based on its current value.
However, if there is an outstanding auto loan, that loan is a liability.
For example:
Car value: $40,000
Auto loan: $25,000
Approximate net contribution:
$40,000 − $25,000 = $15,000
The important point is that the calculation uses the vehicle’s current value and the remaining debt rather than simply the original purchase price.
How Are Business Owners’ Net Worth Estimates Calculated?
Business ownership can make net-worth calculations considerably more complex.
If a person owns 30% of a private company, researchers need an estimate of the company’s value before estimating the owner’s stake.
For example, if a business is estimated to be worth $50 million and an individual owns 30%:
$50 million × 30% = $15 million
That $15 million could potentially represent part of the person’s assets.
However, this is only an illustrative calculation. The actual value of a private ownership stake may depend on the company’s financial performance, valuation methodology, ownership agreements, liquidity, debt, and other factors.
Therefore, business-related net-worth figures should generally be described as estimated unless reliable public evidence establishes a specific value.
Common Mistakes When Calculating Net Worth
Mistake 1: Counting Income as an Asset
Annual salary or earnings are not automatically an asset.
Mistake 2: Ignoring Debt
A person’s assets can look substantial until mortgages, loans, and other liabilities are deducted.
Mistake 3: Using Original Purchase Prices
Current value may be more relevant than what was originally paid.
Mistake 4: Treating Estimates as Facts
This is particularly important when researching celebrity net worth.
Mistake 5: Assuming Ownership
Being associated with a company, brand, property, or investment does not automatically prove full ownership.
Mistake 6: Ignoring Valuation Dates
A person’s net worth can change as asset prices and liabilities change.
Simple Net Worth Calculator Formula
You can use this basic structure:
Step 1: Add cash and bank accounts
Step 2: Add investments and retirement accounts
Step 3: Add real estate and other valuable assets
Step 4: Add business interests where a reasonable valuation is available
Step 5: Add all debts and liabilities
Step 6: Subtract total liabilities from total assets
Formula
Net Worth = Total Assets − Total Liabilities
This is the core answer to “how is net worth calculated?” and is the same fundamental approach used in personal net-worth worksheets from major financial institutions.
Why Net Worth Matters in 2026
Net worth can provide a useful snapshot of financial position, but it should not be viewed in isolation.
Two people with identical net worths may have very different financial situations depending on:
- Their income
- Monthly expenses
- Debt interest rates
- Liquidity
- Investment risk
- Retirement needs
- Tax obligations
- Future financial commitments
The Consumer Financial Protection Bureau also cautions that financial well-being cannot be fully measured through a single number such as income, net worth, or a credit score.
For that reason, net worth is best understood as one financial measurement, not a complete description of someone’s financial health.
Income Sources That Can Increase Net Worth
When people search for how is net worth calculated, they often focus only on salary or annual income. However, income is just one part of the bigger financial picture. Net worth is calculated by taking the total value of assets and subtracting total liabilities. Income can help increase those assets over time, but a person can have a high income and still have a relatively low net worth if they have significant debt, large expenses, or limited savings. The U.S. Securities and Exchange Commission explains the basic calculation as assets minus liabilities.
For this reason, understanding the major sources of income is useful when researching someone’s financial position. Income may come from employment, business ownership, investments, property, intellectual property, endorsements, professional services, or other activities. For celebrities and public figures, researchers may also examine reported salaries, entertainment contracts, sponsorships, business interests, and investment activity. However, reported income should not automatically be treated as net worth because taxes, expenses, debt, ownership percentages, and asset values must also be considered.
1. Salary and Employment Income
For many people, salary is the most straightforward source of income. Employees receive wages, salaries, bonuses, commissions, or other compensation in exchange for their work. Over time, part of this income can contribute to net worth when it is saved or invested.
For example, imagine an employee earns $100,000 per year. That does not mean the person’s net worth automatically increases by $100,000. Income taxes, housing costs, food, transportation, insurance, debt payments, and other expenses reduce the amount available for saving.
If the person saves $20,000 and invests it, those savings become an asset. If the person uses most of the income to pay expenses, the effect on net worth may be much smaller.
This distinction is especially important when reading celebrity net worth articles. A reported salary for a movie, sports season, television contract, or professional engagement is incomenot necessarily an addition of the same amount to net worth.
2. Business Income
Business ownership can be another major source of income and wealth creation. Entrepreneurs may receive money through business profits, distributions, salaries, dividends, or other ownership arrangements.
However, calculating the owner’s net worth requires more than simply adding annual business revenue. Revenue is the money a business receives before expenses. Profit is what remains after relevant business costs are accounted for. The owner’s personal net worth may then depend on the value of the ownership stake and the liabilities associated with it.
For example, someone may own 50% of a company estimated to be worth $10 million. Their theoretical ownership interest could be valued at approximately $5 million, but that does not necessarily mean they have $5 million in cash. The actual value can depend on the company’s debts, financial performance, market conditions, ownership agreements, and whether the valuation is independently verified.
For private companies, these figures can be particularly difficult to establish because detailed financial information may not be publicly available.
3. Investment Income
Investments can produce income through dividends, interest, capital gains, distributions, and other returns. Common investment assets include stocks, bonds, mutual funds, exchange-traded funds, retirement accounts, and other financial instruments.
Investment income can contribute to net worth in two ways. First, the investor may receive cash income. Second, the underlying assets may increase in value.
Suppose someone owns $200,000 worth of investments and those investments rise to $240,000. The additional $40,000 represents an increase in the value of the asset, although it is not necessarily cash income that has been received.
This is why net worth calculations often need a current valuation date. Financial assets can change value regularly. A portfolio worth $1 million at one point could be worth substantially more or less later.
The SEC’s educational resources similarly describe bank accounts, homes, and shares of stock as examples of assets that can be included when assessing financial position.
4. Real Estate Income and Property Value
Real estate can affect net worth through both income and asset appreciation.
A person may earn rental income from apartments, houses, commercial buildings, or other properties. At the same time, the market value of those properties can change.
For net worth purposes, the important calculation is not simply the original purchase price. A researcher may need to consider the property’s current estimated market value and any outstanding mortgage or other debt attached to it.
For example:
Property value: $800,000
Mortgage balance: $500,000
Estimated equity: $300,000
That $300,000 represents the approximate difference between the property’s value and the associated debt.
Real estate valuations can vary considerably depending on location, property type, market conditions, recent comparable sales, and the date of valuation. Therefore, an online net worth estimate should not present an uncertain property valuation as a confirmed cash amount.
5. Rental Income
Rental income is another potential source of recurring cash flow. Property owners may receive rent from residential or commercial tenants.
However, gross rental income should not automatically be treated as profit. Property owners may have expenses such as mortgage payments, property taxes, insurance, maintenance, repairs, management fees, utilities, and periods when a property is vacant.
For example, if a property produces $60,000 in annual rent but requires $25,000 in operating and financing costs, the owner’s available income may be substantially lower than the headline rental figure.
For a net worth calculation, the property itself may be an asset while the mortgage is a liability. The rental income is relevant to the person’s broader financial position but should not simply be added to net worth as though it were another asset.
6. Dividends
Dividends can provide income to shareholders of companies that distribute part of their earnings to investors.
If an investor owns dividend-paying shares, the payments can provide recurring cash flow. If those dividends are saved or reinvested, they can potentially contribute to future asset growth.
For example, an investor with a $500,000 portfolio might receive dividend payments during the year. Those payments are income. If they are reinvested, the investor’s investment holdings can increase.
Nevertheless, the value of the portfolio remains an important part of the net worth calculation. A person with $500,000 in investments does not have a net worth of $500,000 if they also have substantial liabilities.
7. Interest Income
Interest income can come from savings accounts, certificates of deposit, bonds, money-market instruments, and other interest-bearing assets.
Although interest may appear small compared with salary or business income, it can become meaningful when a person has significant financial assets.
For example, someone holding a large cash balance may earn interest throughout the year. If that interest remains in the account, it increases the person’s assets. If it is spent, it does not necessarily increase net worth.
The same principle applies to other forms of income: earning money and accumulating wealth are related but different concepts.
8. Capital Gains
Capital gains occur when an asset increases in value and is sold for more than its purchase price, subject to the applicable tax rules.
For example, an investor purchases shares for $50,000 and later sells them for $80,000. The difference is a $30,000 gain before considering applicable taxes and transaction costs.
Capital gains can also affect net worth through unrealized appreciation. If an investment rises in market value but has not been sold, the owner still holds an asset with a higher current value.
This creates an important distinction between realized and unrealized gains. A net worth estimate may use the current market value of an asset even though the owner has not sold it.
9. Royalties and Intellectual Property
For musicians, authors, actors, producers, inventors, and other creators, intellectual property can generate income through royalties and licensing.
Examples may include:
- Music royalties
- Book royalties
- Film and television rights
- Licensing agreements
- Trademark licensing
- Character rights
- Publishing income
- Patent-related income
The financial value of intellectual property can be difficult to calculate because future income may vary. A successful song, book, film franchise, or character can potentially generate revenue for years, but the amount may depend on contracts, ownership rights, distribution agreements, and future demand.
Therefore, responsible net worth reporting should avoid assigning a precise value to intellectual property without sufficient evidence.
10. Endorsements and Sponsorships
Public figures, athletes, entertainers, influencers, and entrepreneurs may earn money through endorsements and sponsorship agreements.
These arrangements can involve fixed payments, performance-based compensation, appearance fees, affiliate revenue, product partnerships, or equity arrangements.
A reported endorsement deal can indicate an income source, but the exact amount may not always be publicly confirmed. In addition, the gross value of a contract should not automatically be treated as the person’s net wealth.
Taxes, agents, managers, business expenses, contract conditions, and payment schedules can affect the amount ultimately retained.
For this reason, a net worth article should describe sponsorship income as reported or estimated unless reliable documentation confirms the exact figure.
11. Appearance Fees
Some public figures earn money through speaking engagements, event appearances, conferences, private performances, meet-and-greets, or other professional appearances.
These payments can represent meaningful income, particularly for celebrities, entertainers, athletes, entrepreneurs, and public speakers.
However, an appearance fee is still income rather than net worth. To determine its effect on net worth, researchers would need to consider how much of the income was retained, invested, spent, or used to repay debt.
12. Book and Publishing Income
Authors and public figures may earn money from books, memoirs, educational publications, or other written works.
Publishing income can include advances, royalties, licensing payments, and international rights. A successful publication may generate revenue over several years.
However, reported book deals can sometimes represent maximum contract values rather than guaranteed take-home earnings. A careful financial article should distinguish between a reported contract value, an advance, royalty income, and actual earnings whenever information is available.
13. Music and Streaming Revenue
Musicians can generate income from recordings, publishing, streaming, touring, merchandise, licensing, and performance rights.
Streaming platforms may contribute to an artist’s revenue, but the amount reaching an individual artist depends on contracts, ownership structures, labels, publishers, distributors, collaborators, and other parties.
Similarly, gross music revenue is not equivalent to personal income. Production expenses, management fees, label arrangements, taxes, touring costs, and other obligations may reduce the amount ultimately retained.
When calculating net worth, researchers should therefore avoid converting a headline streaming figure directly into personal wealth.
14. Film and Television Income
Actors, producers, directors, writers, and other entertainment professionals may receive income from film and television projects.
Possible sources include:
- Acting salaries
- Producer fees
- Writing fees
- Directing fees
- Bonuses
- Backend participation
- Syndication-related payments
- Licensing arrangements
A reported acting salary may provide useful evidence about earnings, but it does not establish a person’s total net worth.
For example, an actor may earn millions from a production while also paying taxes, commissions, professional expenses, and other costs. The actor may also own investments or businesses that increase net worth independently of entertainment income.
15. Sports Income
Professional athletes may earn money through salaries, bonuses, sponsorships, endorsements, appearance fees, licensing, and business investments.
Sports contracts can sometimes receive substantial media attention, but contract value and personal wealth are not interchangeable.
A multi-year contract may include guaranteed compensation, incentives, signing bonuses, deferred payments, or other provisions. The athlete’s actual financial position can also be affected by taxes, agent fees, investments, spending, and liabilities.
Therefore, a sports salary is best treated as one input into a broader financial analysis rather than as a direct measure of net worth.
16. Social Media and Creator Income
Modern creators can generate income through advertising, sponsorships, memberships, subscriptions, affiliate marketing, merchandise, digital products, and licensing.
YouTube advertising, for example, may generate revenue based on views and advertising activity. But estimated revenue calculators should not be treated as audited financial records.
Creators may also have expenses for editors, managers, production, equipment, advertising, taxes, and other business costs.
If a creator earns $1 million in gross annual revenue, that does not necessarily mean their personal net worth increased by $1 million. The actual change depends on expenses, taxes, savings, investments, debt, and changes in asset values.
17. Merchandise Sales
Merchandise can become a significant income source for entertainers, athletes, creators, and brands.
Products may include clothing, accessories, collectibles, books, cosmetics, or other branded items.
However, merchandise sales represent gross revenue rather than personal profit. Manufacturing, shipping, retailer margins, platform fees, advertising, employees, storage, and other costs must be considered.
For net worth research, it is therefore important to determine whether a reported figure represents sales, business revenue, profit, or personal earnings.
18. Business Equity and Ownership Stakes
One of the most important areas in high-net-worth calculations is business ownership.
Someone may own shares in a private company, publicly traded company, partnership, or other enterprise. The value of those ownership interests can form a significant part of net worth.
Publicly traded shares can generally be valued using the market price multiplied by the number of shares owned. Private-company valuations are more complicated because there may not be a public market price.
Ownership percentages also matter. A person who owns 10% of a business cannot simply be assigned the company’s entire valuation.
In addition, ownership may involve restrictions, debt, preferred shares, voting arrangements, or other contractual conditions.
19. Cash and Bank Accounts
Cash is among the simplest assets to identify.
Bank accounts, savings accounts, checking accounts, and cash holdings may contribute directly to a person’s asset total.
For example:
Checking: $20,000
Savings: $80,000
Cash: $5,000
Total cash-related assets: $105,000
The amount should ideally reflect the relevant valuation date. Bank balances can change frequently, so an estimate based on an old figure may not accurately represent current net worth.
20. Retirement Accounts
Retirement accounts can also be assets in a person’s financial statement. Examples include employer-sponsored retirement plans and individual retirement accounts.
The value of these accounts can contribute to overall net worth, although taxes, withdrawal restrictions, account rules, and valuation methods can differ depending on the account and calculation being performed.
For a general personal net worth statement, the account’s current value can be listed as an asset. However, specialized financial or regulatory definitions may apply different rules.
This is an important reminder that there is no single calculation that automatically applies to every legal, financial, tax, or investment purpose.
21. Vehicles and Personal Property
Cars, motorcycles, boats, jewelry, collectibles, artwork, and other valuable personal property may also be considered assets.
However, valuation can be difficult.
A vehicle’s original purchase price is not necessarily its current value. Depreciation can significantly reduce the market value of cars and other assets.
Similarly, jewelry, artwork, and collectibles may require specialist valuation.
When reliable market evidence is unavailable, a responsible net worth estimate should use a conservative and clearly explained value rather than presenting an unsupported figure as fact.
22. Debts and Liabilities Must Be Subtracted
Income sources alone cannot determine net worth. Liabilities are equally important.
Common liabilities include:
- Mortgages
- Credit-card balances
- Personal loans
- Student loans
- Car loans
- Business debt
- Tax obligations
- Other financial obligations
The SEC’s basic personal net worth guidance specifically instructs individuals to list what they own as assets and what they owe as liabilities, then subtract liabilities from assets.
For example:
Total assets: $2,000,000
Total liabilities: $700,000
Estimated net worth: $1,300,000
This simple calculation demonstrates why income alone cannot answer the question, “How is net worth calculated?”
23. How Income Turns Into Net Worth
Income can increase net worth when it is converted into assets or used to reduce liabilities.
Consider a person who earns $150,000 annually. After taxes and expenses, suppose they have $40,000 remaining.
They could use that money to:
- Build cash savings
- Buy investments
- Pay down debt
- Purchase property
- Contribute to retirement accounts
- Invest in a business
Each decision can affect their balance sheet differently.
If the money is spent completely, the person’s net worth may not increase substantially. If it is invested or used to eliminate debt, the person’s net worth may improve.
This is why financial researchers distinguish between income, wealth, assets, and liabilities.
24. Why High Income Does Not Always Mean High Net Worth
A person can earn a large annual income while having a surprisingly modest net worth.
For example, someone earning $500,000 annually may also have:
- $200,000 in annual expenses
- $150,000 in taxes
- $100,000 in debt payments
- Significant business expenses
If little money remains to accumulate assets, income alone will not create substantial net worth.
Conversely, someone with a moderate salary may build considerable net worth by saving consistently, investing, paying down debt, and accumulating valuable assets over many years.
The Consumer Financial Protection Bureau also notes that financial well-being cannot be measured by a single number such as income or net worth alone.
25. How Celebrity Net Worth Estimates Are Created
Celebrity net worth estimates are usually more complicated than personal calculations because private financial information is often unavailable.
Researchers may examine:
- Publicly reported salaries
- Business ownership
- Company filings
- Property records
- Investment disclosures
- Endorsement reports
- Entertainment contracts
- Public interviews
- Court documents
- Credible media reports
- Known assets and liabilities
The researcher then attempts to construct an estimate from the available evidence.
However, unless the person has publicly disclosed a complete balance sheet or reliable records provide the necessary information, the final number may remain an estimate.
That is why articles should use phrases such as “estimated net worth,” “reported net worth,” or “publicly available information suggests” when the figure has not been independently verified.
26. Why Net Worth Estimates Can Change
Net worth is not necessarily a fixed number.
It can change because of:
- Stock-market movements
- Property-price changes
- Business valuations
- New investments
- Debt repayment
- New borrowing
- Currency movements
- Income and savings
- Major purchases
- Asset sales
- Business performance
For example, if someone owns a large stock portfolio, changes in market prices can affect the estimated value of those assets without the person receiving additional salary.
Likewise, someone who pays down a mortgage reduces liabilities and can increase net worth even without receiving additional income.
27. The Importance of Valuation Dates
Every serious net worth calculation should ideally have a valuation date.
A stock portfolio valued in January may have a different value in September. A property valued several years ago may also have a different market value today.
Therefore, saying that someone has a particular net worth without specifying the relevant period can create a misleading impression of precision.
For online net worth articles, the target year should be clearly stated, such as “Estimated Net Worth in 2026.”
If the underlying evidence comes from different years, that limitation should also be disclosed.
28. Gross Income vs. Net Income
Another common mistake is confusing gross income with money actually retained.
Gross income is generally the amount earned before certain deductions. Net income refers to the amount remaining after applicable deductions and expenses, depending on the context.
For net worth research, neither figure alone determines wealth.
A person’s net worth depends on the assets they own and liabilities they owe at the relevant time. The SEC’s investor education materials use this assets-minus-liabilities framework for calculating net worth.
29. A Simple Net Worth Example
Consider the following hypothetical financial profile:
| Asset | Estimated Value |
| Bank accounts | $100,000 |
| Investments | $350,000 |
| Retirement accounts | $150,000 |
| Home | $600,000 |
| Vehicle | $30,000 |
| Business interest | $250,000 |
| Total Assets | $1,480,000 |
Now consider liabilities:
| Liability | Amount |
| Mortgage | $350,000 |
| Car loan | $15,000 |
| Credit cards | $10,000 |
| Business debt | $50,000 |
| Total Liabilities | $425,000 |
The calculation would be:
$1,480,000 − $425,000 = $1,055,000
The hypothetical net worth would therefore be $1.055 million.
This example shows why simply adding salaries, business revenue, or investment income does not produce a net worth figure.
30. What Makes a Net Worth Estimate Reliable?
A strong net worth estimate should be based on evidence rather than speculation.
Useful evidence can include official filings, documented ownership, credible financial reports, property records, known investments, and clearly explained calculations.
The quality of an estimate also depends on whether the researcher accounts for liabilities. A person may have valuable assets but significant debt that materially reduces their net worth.
The SEC’s educational material emphasizes maintaining a net worth statement by tracking both what you own and what you owe.
For public figures, complete financial information is rarely available. Therefore, transparency about uncertainty is an important part of trustworthy financial content.
Frequently Asked Questions
1. How is net worth calculated?
Net worth is generally calculated by subtracting total liabilities from total assets. Net Worth = Assets − Liabilities.
2. What counts as an asset when calculating net worth?
Assets can include cash, bank accounts, investments, real estate, retirement accounts, businesses, vehicles, and other items with financial value.
3. What counts as a liability?
Liabilities can include mortgages, credit-card balances, student loans, car loans, personal loans, business debt, and other financial obligations.
4. Is income the same as net worth?
No. Income is money earned or received, while net worth measures the value of assets after subtracting liabilities. A high income does not automatically mean a high net worth.
5. How is celebrity net worth calculated?
Celebrity net worth is usually estimated using publicly available information about income, assets, businesses, investments, property, contracts, and liabilities. Because private financial information may be unavailable, these figures are often estimates.
6. Does a house count toward net worth?
Generally, yes, for an ordinary personal net worth statement, a home can be included as an asset while the related mortgage is a liability. However, specialized financial or regulatory calculations can use different rules.
7. Do cars count as part of net worth?
Yes. A vehicle can be treated as an asset, typically using a reasonable current market value rather than its original purchase price.
8. Can investments increase net worth?
Yes. Investments can increase net worth when their value rises or when income is saved and reinvested. However, investment values can also fall, causing net worth to decrease.
9. Why do celebrity net worth estimates differ between websites?
Different websites may use different sources, asset valuations, ownership assumptions, debt estimates, and calculation methods. Private financial information can also make exact verification difficult.
10. How often should net worth be calculated?
For personal financial planning, regularly updating a net worth statement can help track changes over time. The SEC’s investor education guidance recommends updating a net worth statement annually.
Conclusion
Understanding how net worth is calculated becomes much easier when you focus on one simple formula: total assets minus total liabilities. Income from salaries, businesses, investments, real estate, royalties, sponsorships, and other sources can help build wealth, but income itself is not the same as net worth. For celebrities and public figures, the calculation can be more complicated because complete details about private assets, debts, taxes, and ownership stakes are often unavailable.
That is why many online net worth figures should be treated as estimates rather than confirmed financial statements. A reliable calculation should use credible evidence, reasonable asset valuations, and clearly identified liabilities. By understanding the difference between income, assets, liabilities, and net worth, readers can better evaluate financial claims and recognize why reported wealth figures may vary from one source to another.